In Podcast Episode #210 of Healthcare Redefined—Advocating for Aging Adults and Their Families, we interviewed two Medicare advisors—Wendi Schoonover (Integrity Insurance Group) and Kevin McGuire (Tailored Health Designs)—to share practical ways to prepare for Medicare Annual Enrollment for 2027 coverage.
If you’re thinking, “I’ll deal with Medicare during enrollment,” you’re not alone. But every year, families lose money (and peace of mind) because they wait too long or compare plans the wrong way.
Listen to the full episode here: https://yournurseadvocateconsulting.com/2026/09/10-medicare-changes-for-2027/
Important: This article is for education only. It is not legal, financial, or medical advice. Your situation is unique—talk with a qualified professional about your specific needs.
Medicare Annual Enrollment vs Open Enrollment (What’s the Difference?)
Medicare has a few different enrollment windows, and the names can be confusing.
Medicare Annual Enrollment Period (AEP)
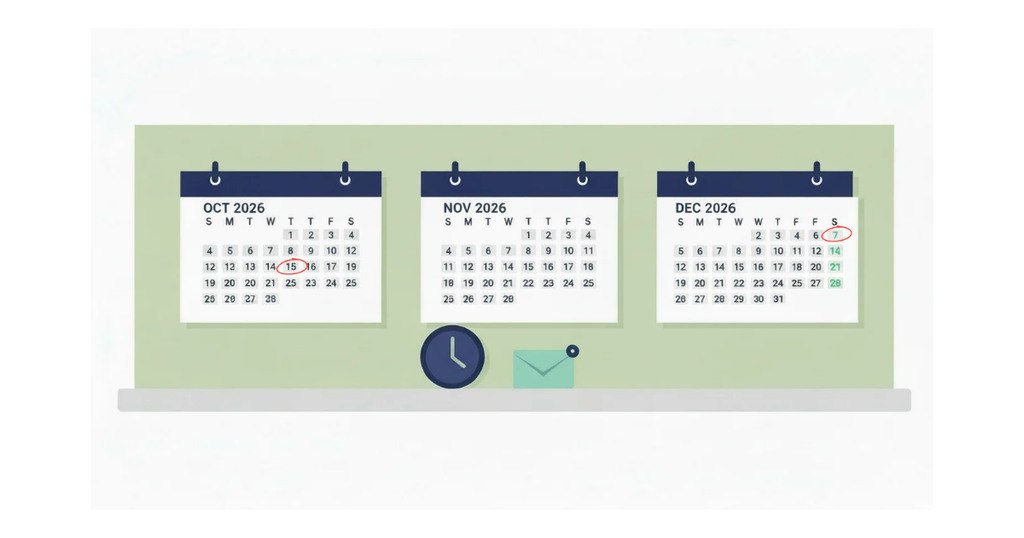
During Annual Enrollment, you can review and change coverage for the upcoming year. In the episode, Kevin explained that you’ll start seeing plan information in early October, and changes can be made starting October 15 through December 7, taking effect January 1, 2027
Medicare Advantage Open Enrollment (MA OEP)
Kevin also described a separate window (often called “open enrollment”) that applies to people already on Medicare Advantage. This runs January 1 through March 31 and can be used to re-evaluate a decision made during Annual Enrollment.
The #1 Mistake Families Make During Annual Enrollment
Both guests agreed on a theme: people either don’t look at their plan at all, or they “look” but rely on advice from someone who isn’t licensed to review plans.
Wendi put it plainly: don’t choose a plan because “my brother said…” Your medications, budget, preferences, and travel plans are different—so your Medicare choice should be personalized.
Medicare Annual Enrollment Dates: What to Watch For
One practical tip from Wendi: you’ll receive an Annual Notice of Change (ANOC). Don’t toss it. It often includes key updates like premium changes, network changes, and coverage changes.
If you’re helping a parent, consider making a simple system: keep Medicare mail in one folder until you’ve reviewed it or shared it with a trusted advisor.
A Simple Checklist for Reviewing Your 2027 Medicare Options
Use this as your “bring-to-the-appointment” list.
1) Update your medication list (name, dose, and form)
Kevin stressed that your list needs to be accurate and current—including dosage and whether it’s a tablet vs capsule, because pricing can change.
Pam shared a real example: entering a brand name vs the generic name can create a huge price difference.
2) Confirm your pharmacy (in-network and preferred)
Drug plans often have an in-network list and a preferred list. Your cost can change based on where you fill prescriptions (including mail order).
3) Check your doctors, clinics, and hospitals
Kevin’s biggest red flag: if a plan doesn’t include the doctors you want to keep.
Linda shared an example where one clinic in a health system dropped out of a plan network while other clinics stayed in—so it’s worth checking each year.
4) Review travel needs (snowbirds and two-state living)
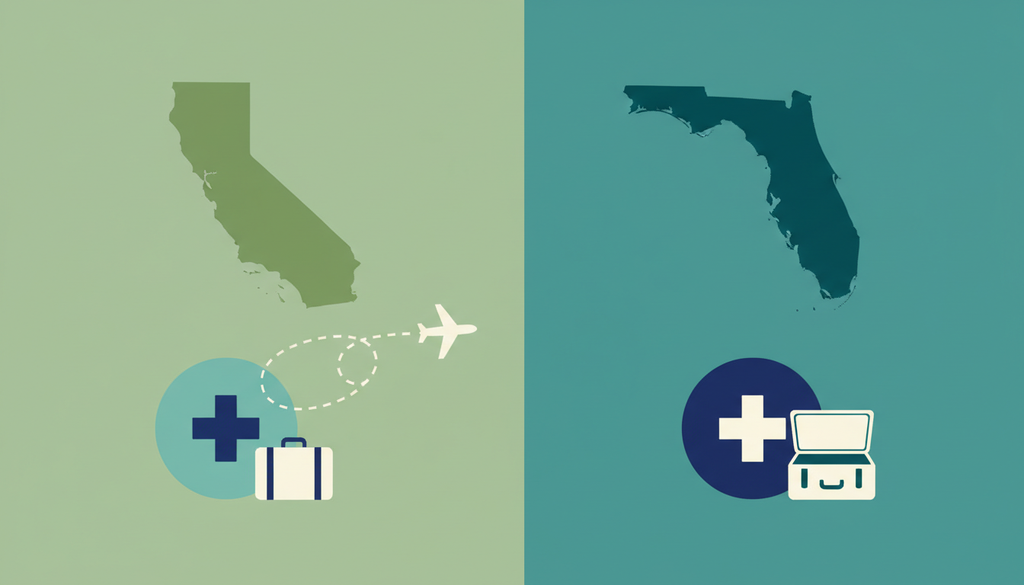
Wendi recommended starting with one key question: will you need routine care while you’re away, or only emergency coverage?
Emergency care is typically covered anywhere. Routine care can be different depending on whether you have Original Medicare, a Supplement, an HMO, or a PPO.
5) Compare total yearly cost (not just the monthly premium)
A “$0 premium” plan can still cost you money through copays, deductibles, and out-of-pocket maximums.
Kevin’s approach: think through how you expect to use care in the coming year (appointments, planned procedures, dental work, vision needs). Linda added: ask yourself what your health goals are for the year ahead.
Medicare Advantage vs Medigap (Supplement): How Families Decide
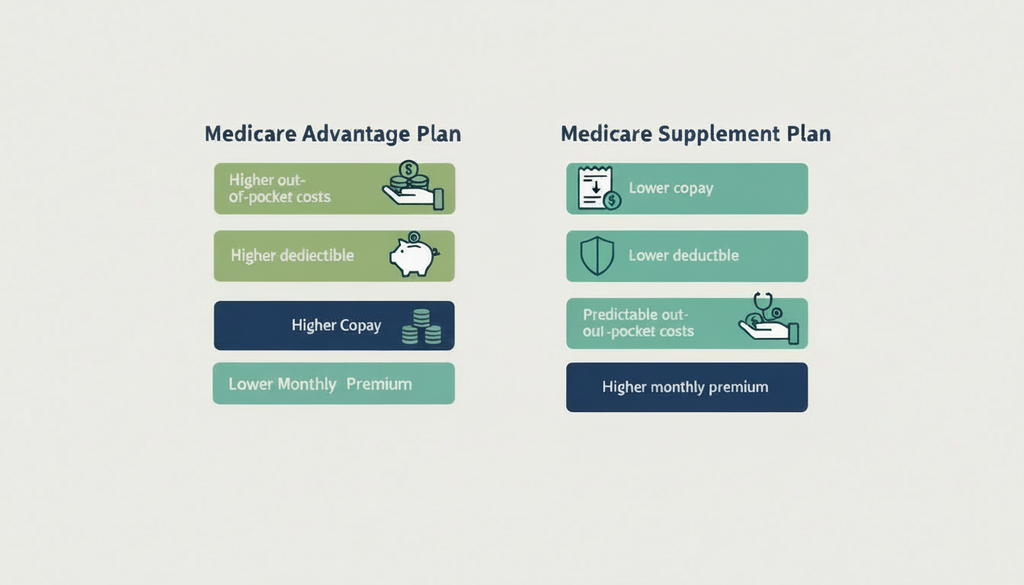
Kevin explained it well: a Supplement often costs more up front, but can feel simpler when you use care. Medicare Advantage can cost less up front, but you may pay more as you use services.
Wendi’s simple framing was: Do you want to pay in advance for the “just in case,” or pay as you use it? Then ask yourself: if you hit the plan’s out-of-pocket maximum, would you be okay paying that amount?
Don’t Get Tricked by “$0 Premium” Plans
Wendi said it directly: people hear “zero premium” and think it means “free.” It doesn’t.
A $0 premium Medicare Advantage plan means you’re not paying an additional premium on top of your Part B premium. You still need to understand copays, networks, prior authorizations, and prescription costs.
If You’re Helping a Parent Choose Medicare, Support Without Taking Over
Kevin’s advice: make space for your parent to be heard. This can be a scary transition for someone who has been independent for a long time.
Wendi added a helpful question for adult children: How involved will you be? If you’re going to help with bills and prior authorizations, that may shape what plan feels realistic for your family.
Key Takeaways (Quick Recap)
· Don’t wait until the last minute—review early and plan ahead.
· Bring an accurate medication list (name, dose, form) and confirm your pharmacy.
· Verify doctors, clinics, and hospital networks every year.
· Consider travel and whether you’ll need routine care in another state.
· Compare total yearly cost, not just the monthly premium.
· Don’t rely on internet advice or a friend’s plan choice—your situation is unique.
Listen to the Full Episode
For the full conversation with Wendi Schoonover and Kevin McGuire, listen to Healthcare Redefined—Advocating for Aging Adults and Their Families:
If you’re looking for support as you navigate aging, caregiving, or healthcare decisions, Your Nurse Advocate Consulting is here to help.
FAQ: Medicare Annual Enrollment for 2027 Coverage
What can I change during Medicare Annual Enrollment?
You can review and change Medicare Advantage plans and Part D drug plans during the Annual Enrollment window. The last change you make during the period is the one that takes effect January 1.
Do I really need to review my Part D plan every year?
Yes. Wendi and Kevin both emphasized that drug plans can be volatile. Premiums, deductibles, and formularies can change year to year.
What should I bring to a Medicare plan review appointment?
Bring your current medication list (with dose and form), your preferred pharmacy, your doctors and clinics, and notes about expected healthcare needs (travel, planned procedures, new diagnoses).
Is a $0 premium Medicare Advantage plan really free?
No. “$0 premium” means no additional plan premium beyond your Part B premium. You still need to understand copays, networks, and out-of-pocket limits.
Thank you for spending time with us this week. We’re so glad to be part of your journey in caring for your aging loved ones. It’s an honor to share resources, insights, and a little encouragement to support you along the way. We look forward to bringing you more helpful tools and compassionate guidance in the weeks ahead. See you back here soon!
With care,
Pam and Linda
Your Nurse Advocates
“Compassionate Care for Aging Adults Along With Peace of Mind for the Family”
Resources:
Free Tool Kit: Preparing to meet with your Medicare Advisor
Video: Documents to help you prepare for Medicare Annual Enrollment
Medicare Website for Changing or Selecting Your Plan
National Council on Aging: 3 Ways to Prepare for Medicare Open Enrollment
Integrity Insurance Group: Wendi Schoonover
Kevin McGuire Tailored Health Designs
About the Authors
At Your Nurse Advocate Consulting, Pam and Linda’s mission is to empower aging adults and their families to take control of their health, prepare for life’s uncertainties, and secure their peace of mind. We are dedicated to providing compassionate guidance, personalized support, and expert resources to help our clients navigate complex medical needs and organize their personal affairs.
As independent patient advocates we have a steadfast commitment to clarity, family well-being, and empowerment, we strive to make a meaningful impact by ensuring our clients feel confident, prepared, and cared for every step of the way on their healthcare journey.
Expert Guidance You Can Trust
With over 80 combined years of R.N. experience navigating the complex healthcare system, we stand as trusted guides for seniors and their families. Our expertise ensures they can access the care and resources they need without feeling overwhelmed by red tape or confusion.
Medical Disclaimer
The information provided in our emails and all forms of content including but not limited to podcasts, blog posts, videos, or social media posts are for informational purposes only and is not intended to substitute professional medical advice, diagnosis, or treatment. Always seek the advice of your physician or other qualified healthcare provider with any questions you may have regarding a medical condition or care plan. Never disregard professional medical advice or delay seeking medical care because of something you have read here. Your health and well-being are our top priority.